Keep your first mortgage · No branch visit · One broker, start to finish
Turn the equity you’ve built into cash you can use.
A home equity line sits behind the mortgage you already have, so the rate you locked years ago stays exactly where it is. Up to $750,000, funded in as few as 5 business days.
- No tax returns, no docs
- Terms of 5, 10, 15 or 30 years
- 1st, 2nd or 3rd lien position
See what’s available
1 / 12
What do you need the cash for?
There's no wrong answer — the line isn't restricted by what you spend it on.
No hard credit pull. No Social Security number. Your information is never sold.
 Work directlywith Phil
Estimators
Run the numbers.
What the minimum payment actually costs you, at the national average rate of 25%.
- Paid off in
- 38 yr 9 mo
- Interest
- $103,032
- Total paid
- $153,032
- Paid off in
- 20 years
- Interest
- $50,298
- Total paid
- $100,298
That’s $52,734 less interest, and 18 yr 9 mo sooner.
The 7.99% annual percentage rate shown is for illustration only and is not an offer of credit. Your actual rate depends on your credit, combined loan-to-value, lien position, occupancy, property type and term, and will differ. Home equity lines of credit carry a variable rate that may increase; the maximum ANNUAL PERCENTAGE RATE that may be imposed is 18.00%. Figures show principal and interest only and do not include taxes, insurance, homeowners association dues, closing costs or any origination fee. A home equity line of credit is secured by your dwelling — if you do not repay it, you could lose your home. This calculator is an educational tool, not a commitment to lend, and does not represent terms available to any particular consumer. Credit card figures assume a 25% annual percentage rate and a minimum payment of 1% of the balance plus accrued interest, with a $25 minimum; your card's terms will differ.
Reviews
What our clients say about us.
★★★★★
Working with Phil was an amazing experience. From our very first phone call, he took the time to explain everything in a way that was easy to understand… Our refinance process took longer than expected because of delays on our end, but Phil was incredibly patient and consistently checked in with us throughout the entire process. He's someone you can trust, and I couldn't be happier with our experience.
★★★★★
I highly recommend Mr. Phillip Nadaski and his team! Their professionalism, communication, and follow-up are second to none. Every question I had was answered promptly, and I was kept informed throughout every step of the loan process. Everything happened exactly as promised, making the experience smooth and stress free.
★★★★★
Hats off to Phil! He was able to take an extremely difficult loan situation and make an absolute success out of it. From start to finish his level of communication, thoroughness and professionalism led the way. Both my husband and I want to thank Phil for all of his hard work.
★★★★★
Phil was amazing throughout my refinance. Clear communication, honest guidance, and zero stress from start to finish. He explained every step and made the process easy. I'd absolutely recommend him and will use him again in the future.
Why a line, not a refinance
Borrow against it. Keep it.
A cash-out refinance replaces the mortgage you already have. A line of credit sits behind it, so the rate you locked stays where it is.
Keep your first mortgage
A standalone line sits behind the mortgage you already have, so the rate you locked years ago stays exactly where it is.
Up to $750,000
In 1st, 2nd or 3rd lien position, with terms of 10, 15, 20 or 30 years.
Funded in as few as 5 days2
Apply in minutes online. No branch visit, no paper application, no waiting weeks for an answer.
Cheaper than the alternatives1
Lower rates than personal loans and credit cards for the same borrowing.
1Bankrate data for Personal Loan, Credit Cards, and HELOC. The HELOC product requires the customer to pledge their home as collateral, and the customer could lose their home if they fail to repay.
2Approval may be granted in five minutes but is ultimately subject to verification of income and employment, as well as verification that your property is in at least average condition with a property condition report. Five business day closing assumes closing the loan with our remote online notary. Closing timelines will be longer for loans secured by properties located in counties that do not permit recording of e-signatures or that otherwise require an in-person closing.
What it’s for
Four reasons people open one.
Consolidate high-interest debt
Credit cards at 22% become one payment at a fraction of the rate. This is the most common reason people open a line, and usually the one that saves the most.
Renovate the house
Kitchens, roofs, additions, solar. Borrow against the value you've already built rather than financing at retail rates.
Cover a large expense
Tuition, a medical bill, a wedding, a business opportunity. The line sits there whether you draw on it or not.
Keep cash available
Open it before you need it. An approved line you haven't drawn costs nothing and takes five days to arrange, not five weeks.
How it works
Four steps, no mystery.
- 01
Tell us the basics
Your home's value, what you owe, and how much you're after. Two minutes, and no hard credit pull.
- 02
We check the numbers
Phil reviews what you sent and calls you the same business day with what's actually available and what it would cost.
- 03
Apply online
The full application is digital and takes minutes. Approval can come back in five.
- 04
Close and draw
Signing is done remotely with an online notary. Funding in as few as five business days.
Funded
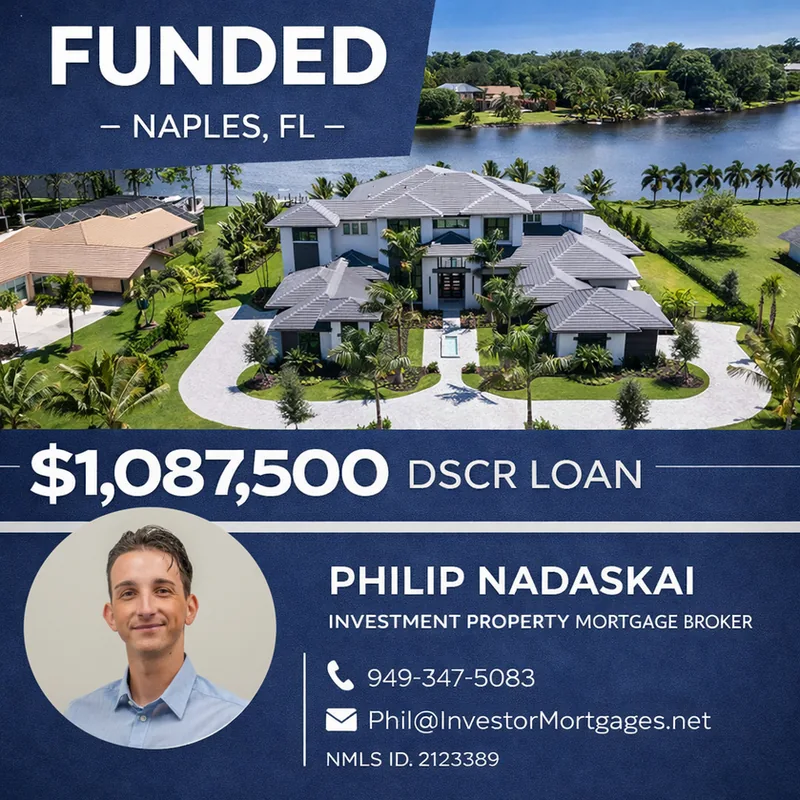
$1,087,500 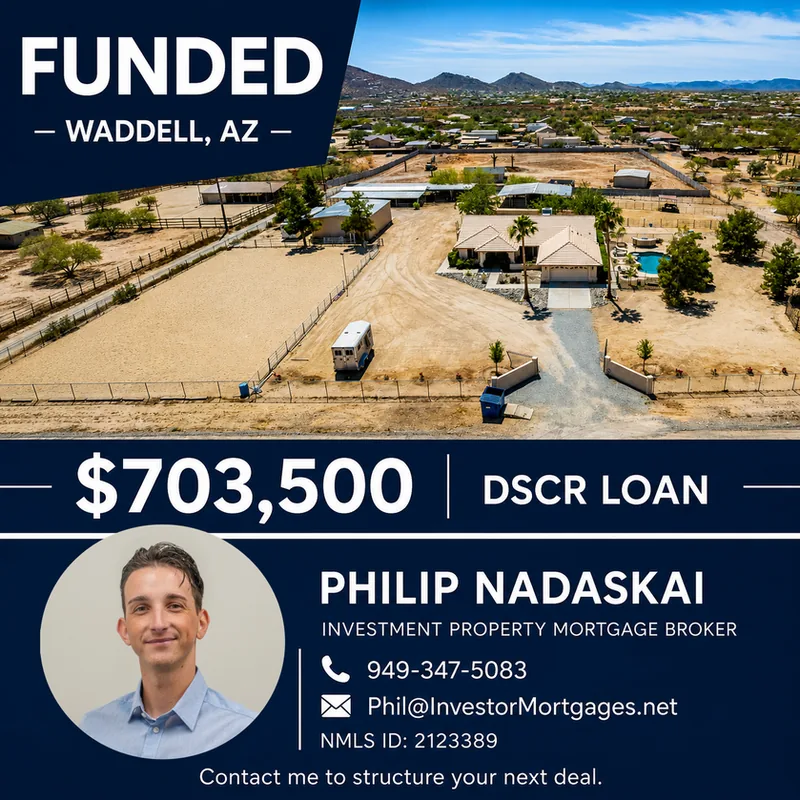
$703,500 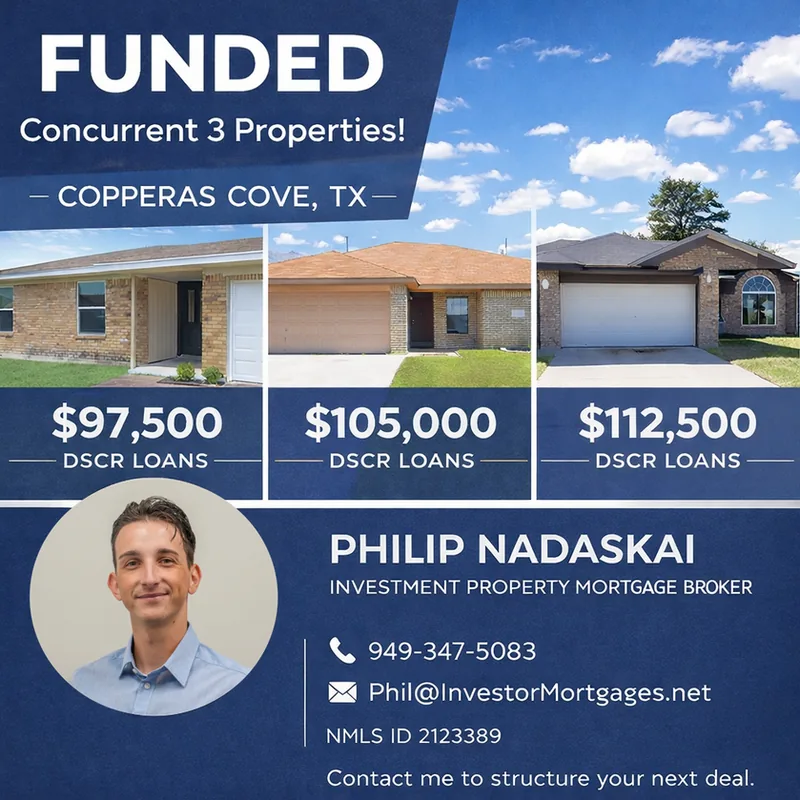
3 loans funded 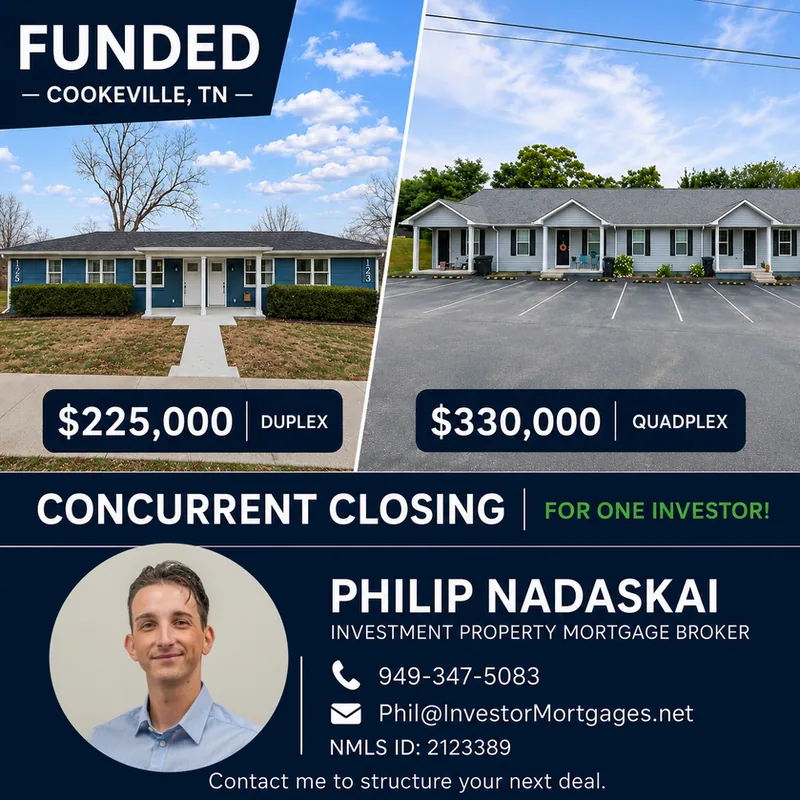
2 multi-family funded 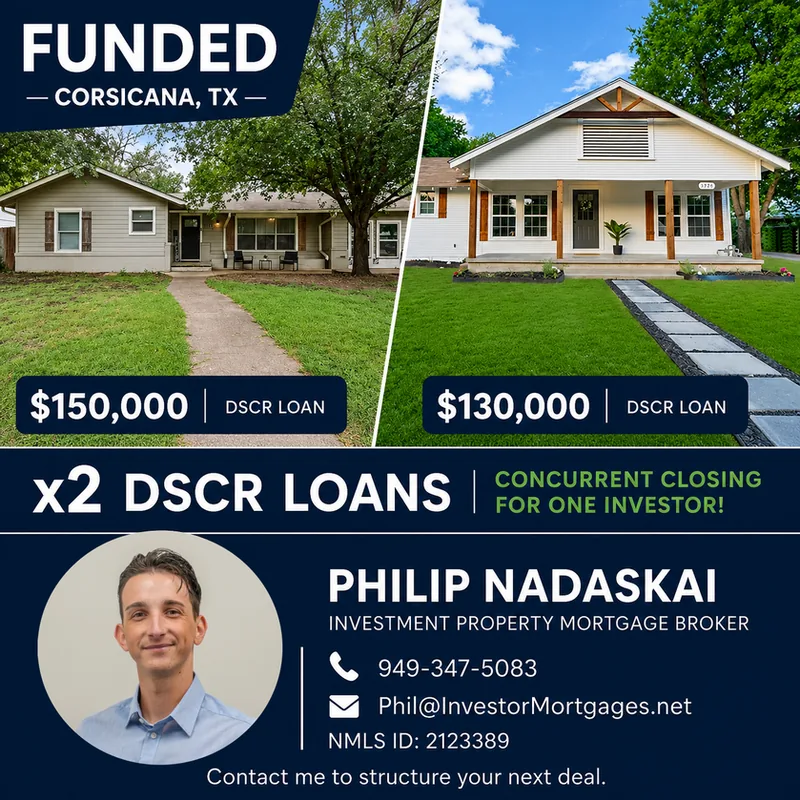
2 SFR funded concurrently 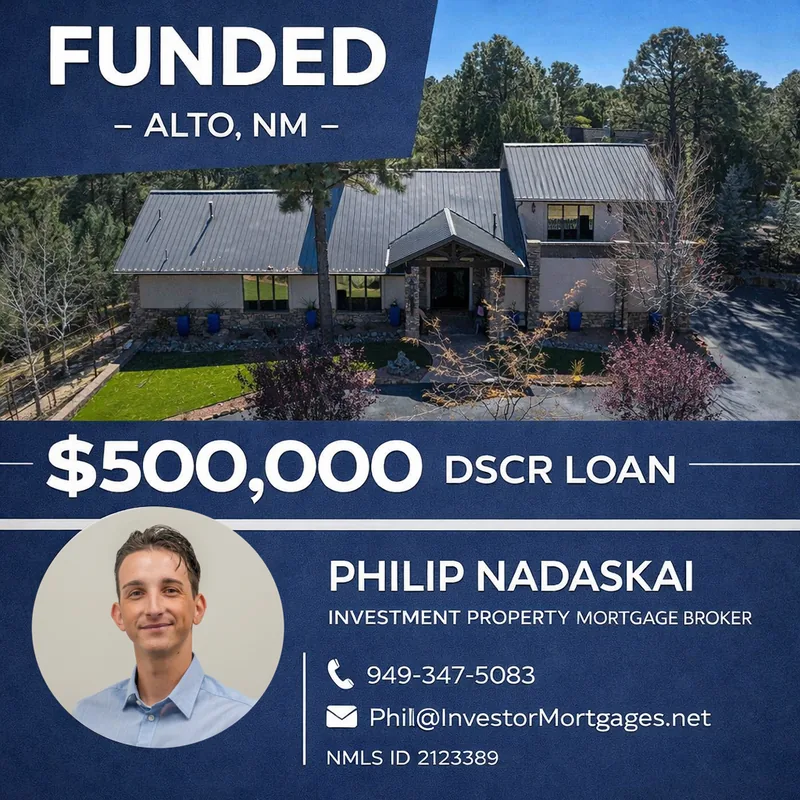
$500,000 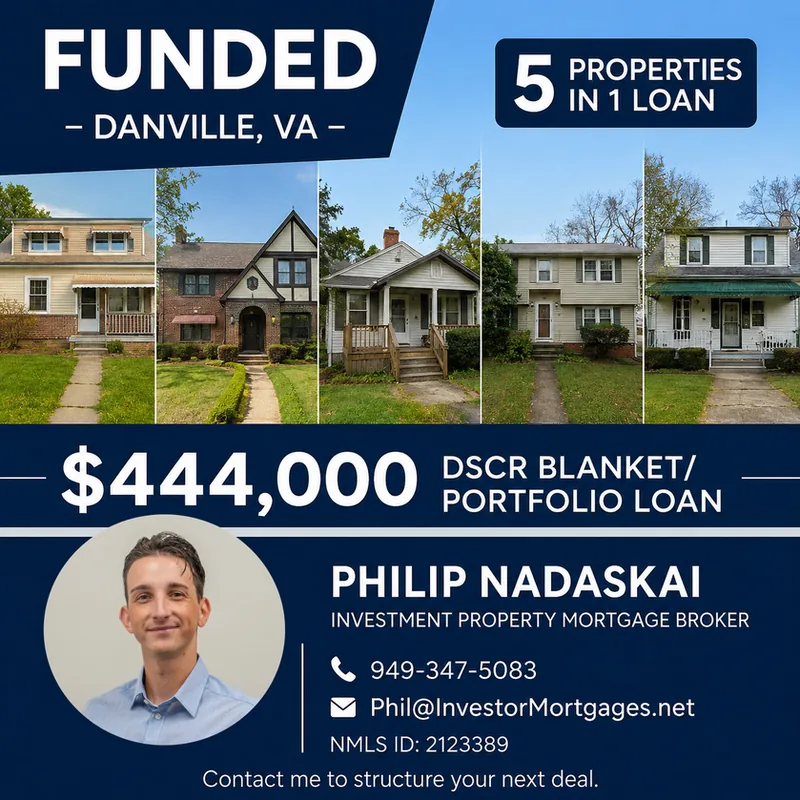
$444,000 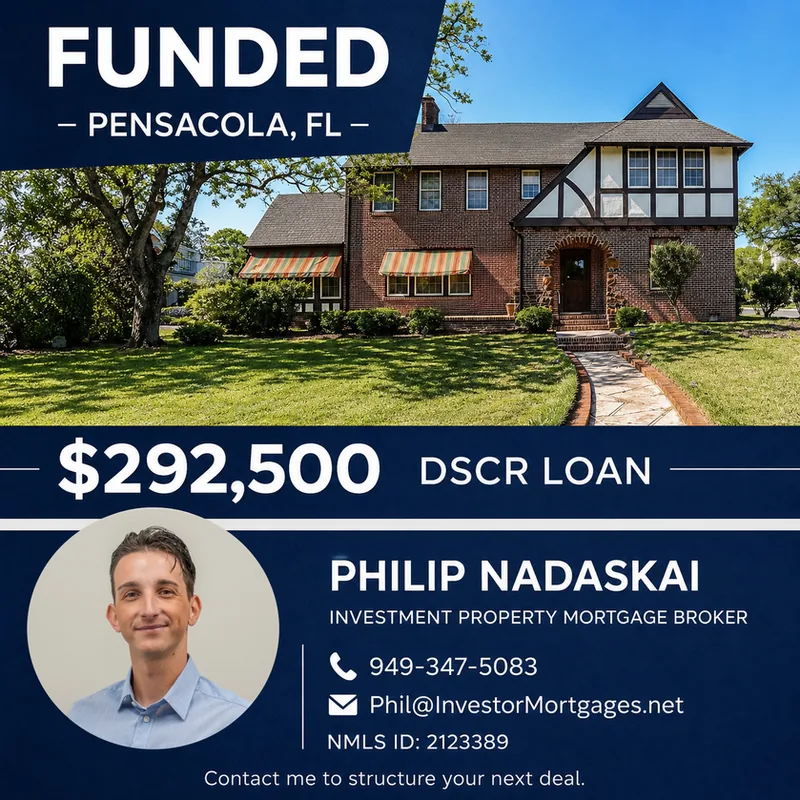
$292,500 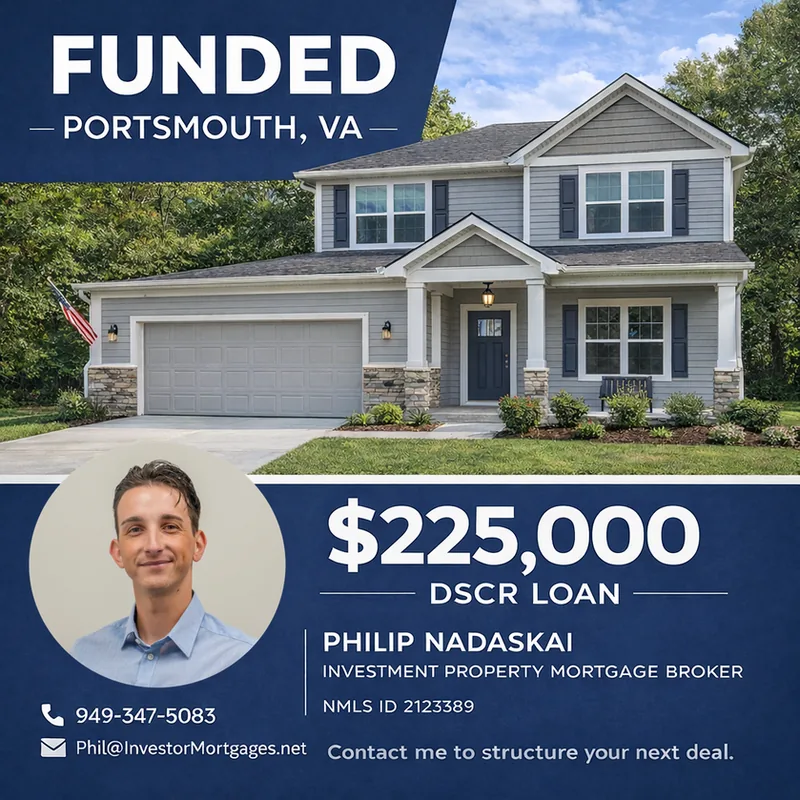
$225,000 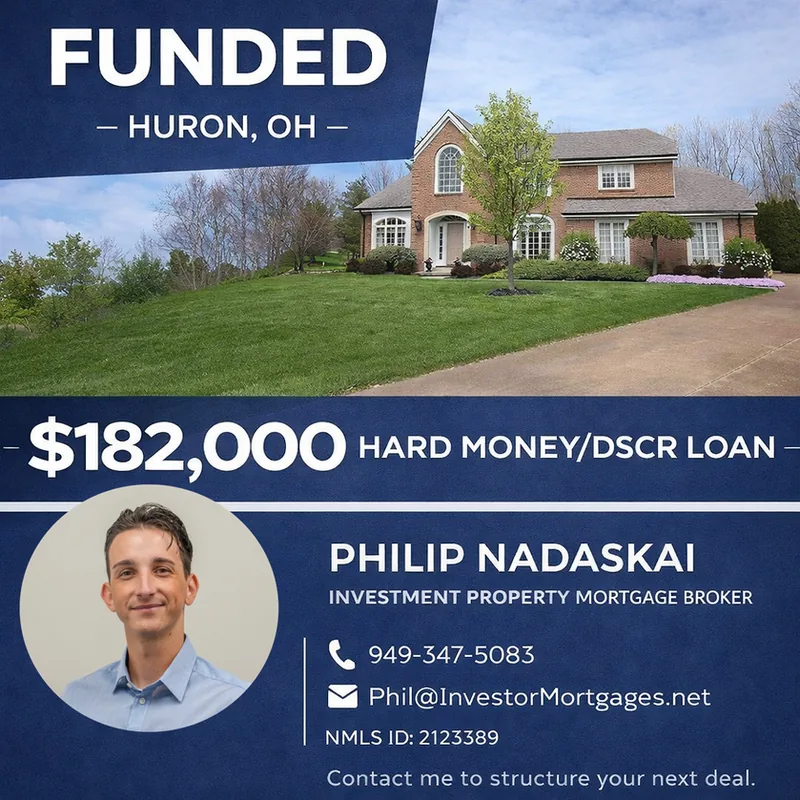
$182,000 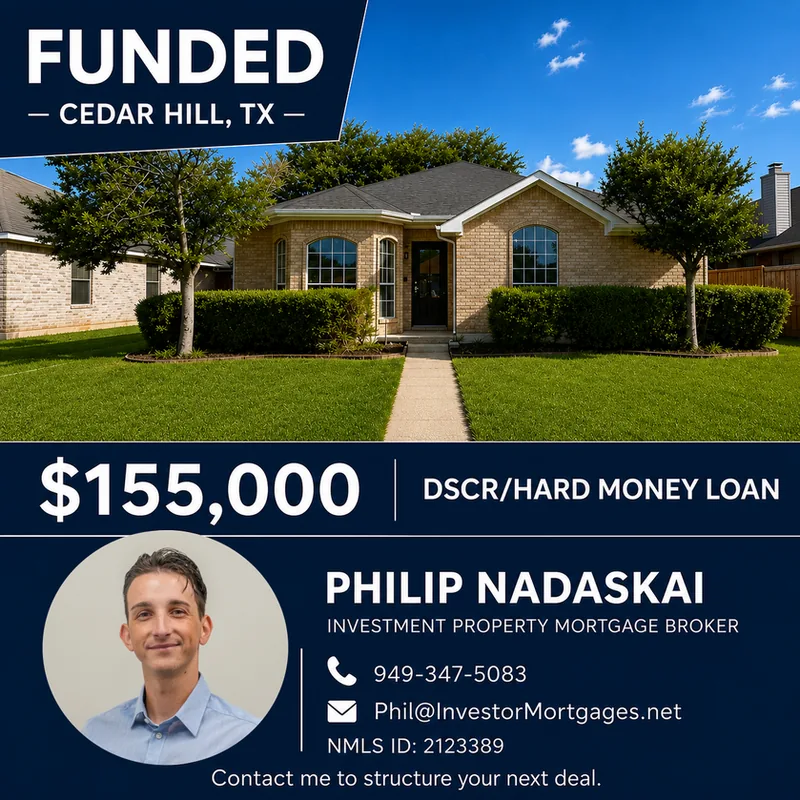
$155,000 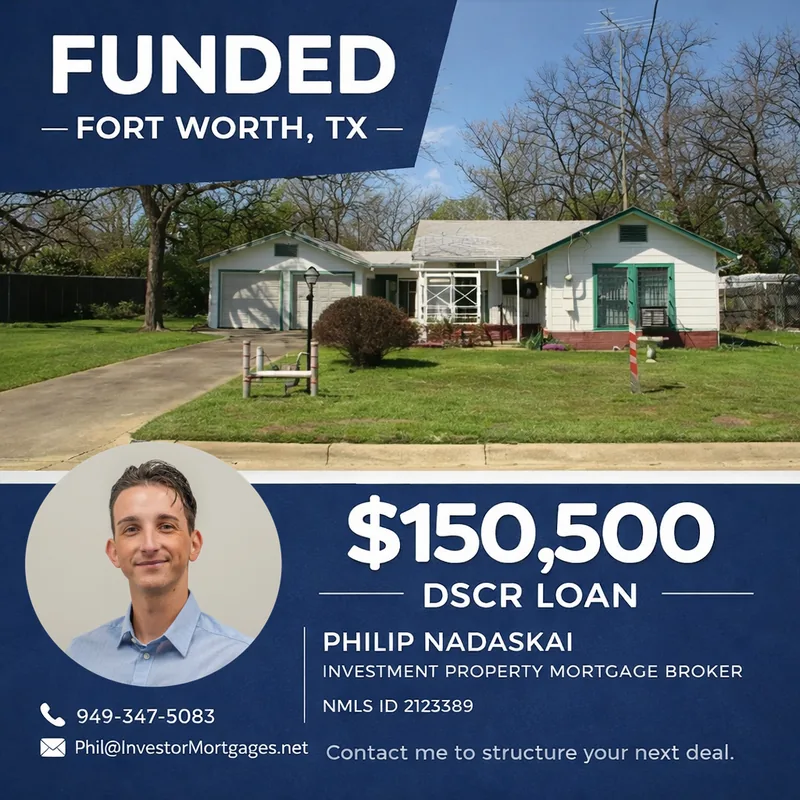
$150,500 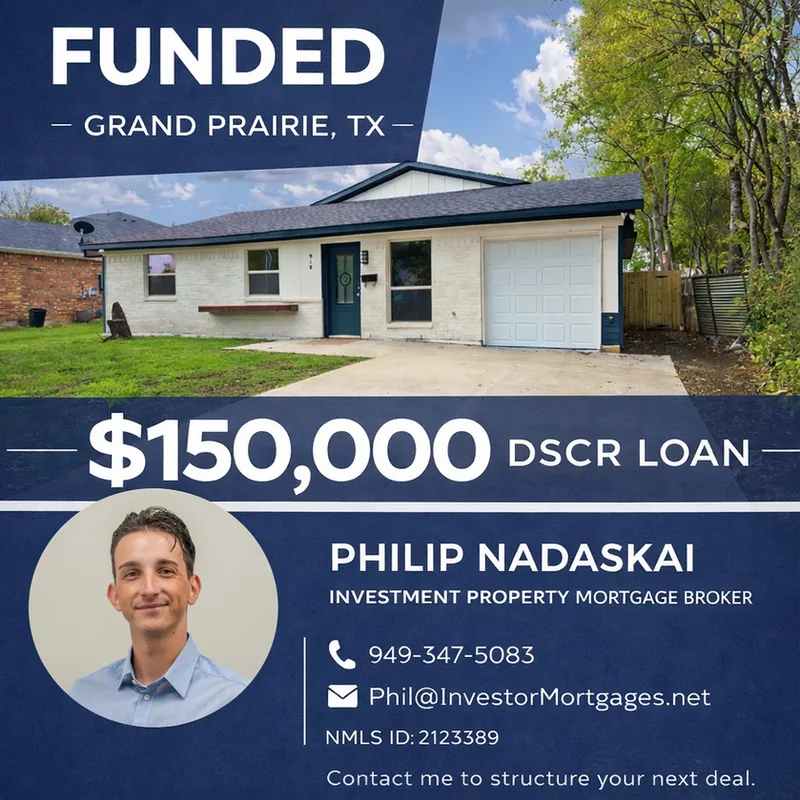
$150,000 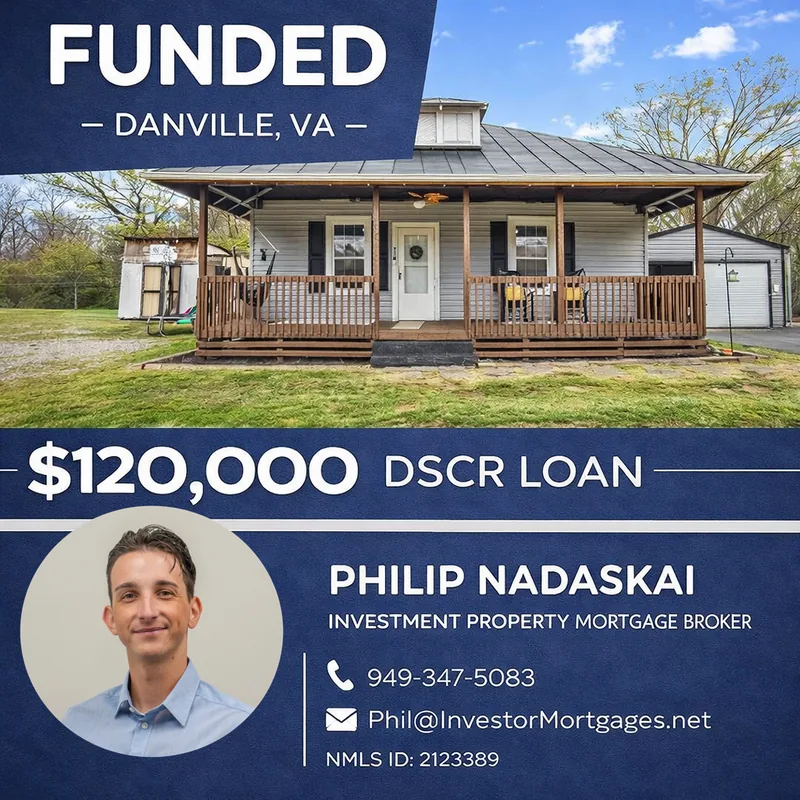
$120,000 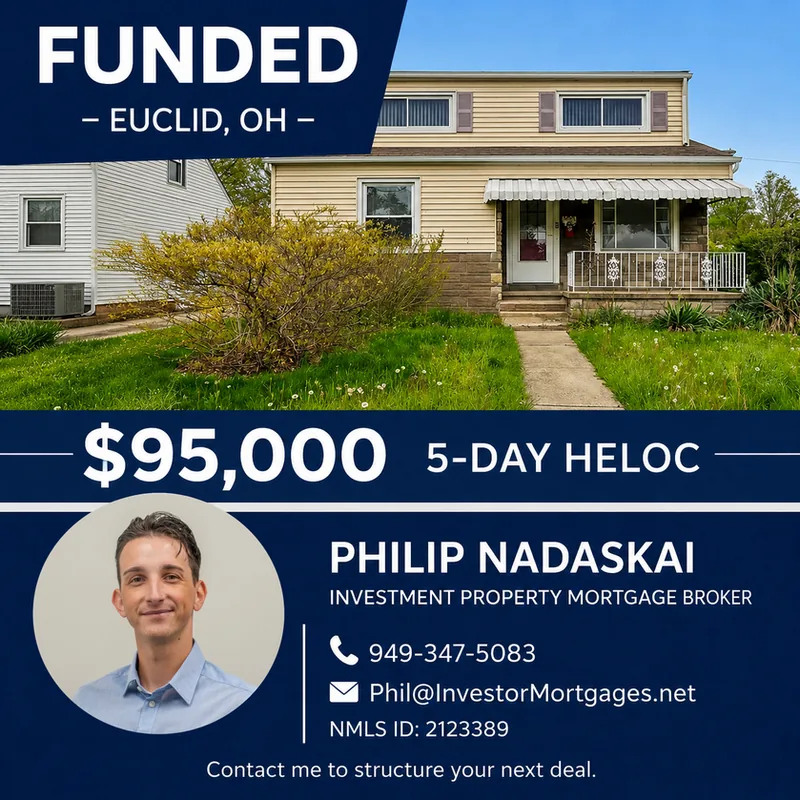
$95,000 
$65,000
Coverage
Where we lend.
Select a state to see what’s available there.
Too small to click on the map
- Lending available
- Not licensed
Your broker
Philip Nadaskai
One licensed broker handles your file from the first call through closing. No call center, no hand-offs, and your information isn’t sold to a panel of lenders who then all phone you.
Borrowing against your home is a serious decision, and the goal here isn’t one closing — which is exactly why you’ll hear it when a line of credit isn’t the right tool for what you’re trying to do.
Questions, answered
Before you ask.
No, and that's the point. This is a standalone line that sits behind whatever mortgage you already have. If you locked something low a few years ago, a cash-out refinance would mean giving that rate up on the entire balance. A line of credit leaves it alone.
The calculators are anonymous — nothing is sent and nothing is checked. When you submit the form you're asked to authorise a soft credit check, which lets us quote you accurately. A soft check has no effect on your score and doesn't appear to other lenders as an inquiry. A hard pull only happens later, separately, and only if you decide to go ahead with an application.
It depends on what your home is worth, what you still owe, your credit and how the property is used. Lines run up to 85% of the home's value minus what you already owe, and up to $750,000. Above $400,000 the requirements tighten — a higher credit score, owner-occupied only, and a full appraisal. The estimator above gives you a rough figure in a few seconds.
Anything. Debt consolidation and home improvement are the most common, but there's no restriction — the line is secured by your home, not by what you spend it on.
No. It's a line of credit, so you draw what you need when you need it. Many people open one and leave it sitting there as a safety net.
Approval can come back in about five minutes, and funding in as few as five business days if you close with the remote online notary. Some counties don't permit electronic recording and require an in-person closing, which takes longer.
It's a real one and worth saying plainly: this loan is secured by your home. If you don't repay it, you could lose the property. That's why the rate is lower than a credit card — the lender has recourse. Borrow what you can comfortably repay.
Philip Nadaskai, a licensed mortgage broker. One person handles your file from the first call through closing. Your information isn't sold and isn't distributed to a panel of lenders who then all phone you.
Find out in two minutes.
No hard credit pull, no obligation, and a straight answer either way — including when the answer is no.